Consumer finance market research is becoming more important as technology changes not only how financial products are delivered, but what consumers expect those products to do. Bank accounts, credit cards, mortgages and lines of credit are not disappearing. Instead, artificial intelligence (AI), mobile technology, real-time payments and increasingly personalized digital experiences are changing how consumers discover, evaluate and use them.
That creates an important challenge for banks, fintech companies and other financial services providers. Technology can make a financial product faster or more sophisticated, but it cannot guarantee that consumers will understand it, trust it or use it.
The future of consumer finance will therefore depend on two things happening at the same time: continued technological innovation and better understanding of the consumers expected to adopt it.
Traditional Consumer Finance Products Are Becoming Digital Products
The basic architecture of consumer finance remains familiar.
Consumers still need:
- Checking and savings accounts
- Credit cards
- Mortgages
- Personal loans and lines of credit
- Payment services
- Savings and investment products
What is changing is the experience surrounding those products.
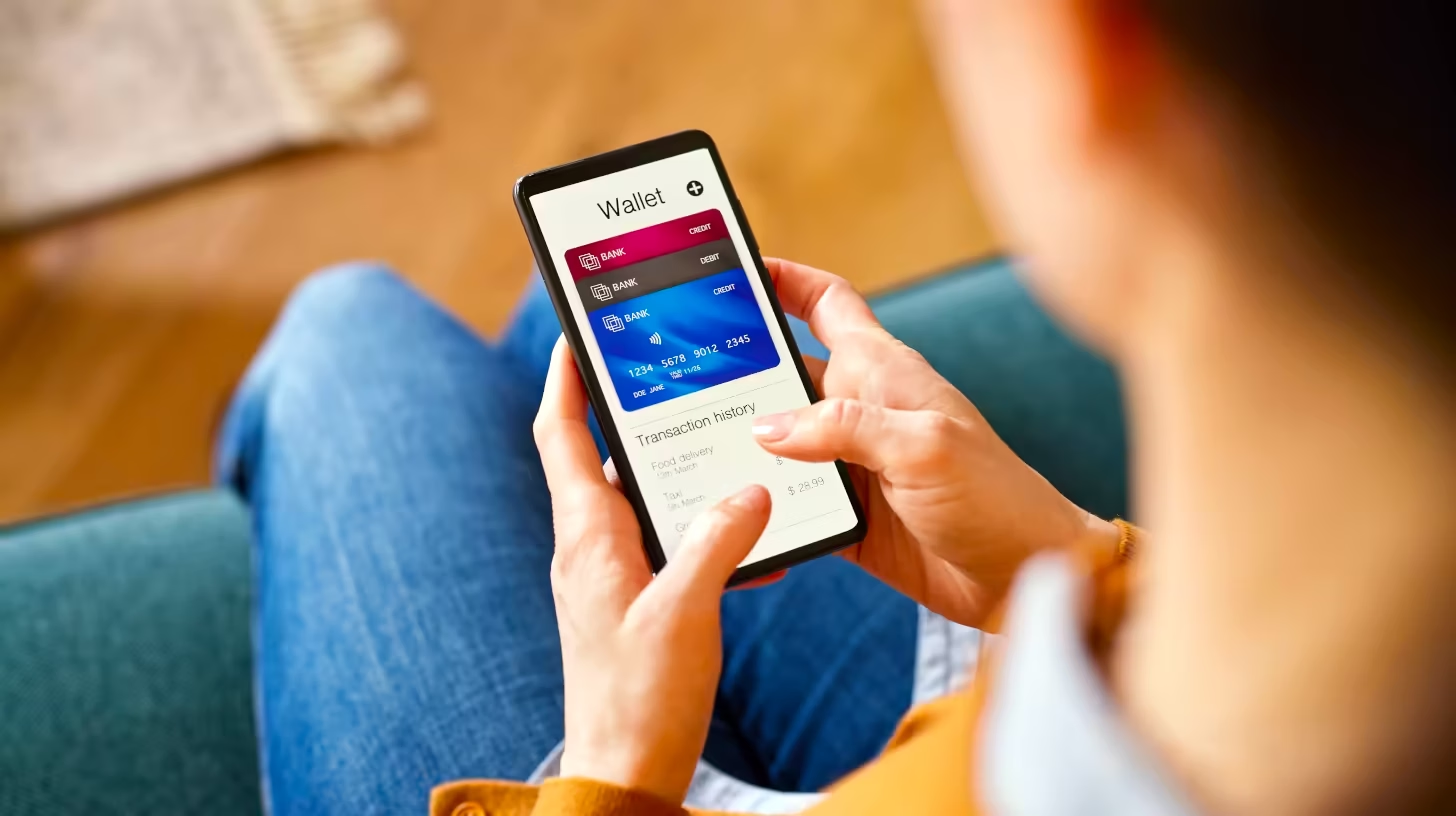
A checking account, for example, is no longer simply a place to deposit money. Consumers increasingly expect mobile access, instant transaction alerts, digital payments, automated insights, seamless transfers and increasingly personalized financial guidance.
The same applies to credit. Credit cards can now include real-time spending information, personalized offers and automated fraud detection. Mortgage customers can complete increasingly large portions of the application and underwriting process digitally. Personal lenders can use alternative data and automated decision-making to evaluate applicants faster.
In the United States, this transition is visible across the payments system. The Federal Reserve reported that consumers and businesses made 236.6 billion noncash payments in 2024, more than three times the number recorded in 2000. Cards represented more than three-quarters of those payments by number. (Federal Reserve)
Traditional consumer financial products therefore are not necessarily being displaced. They are becoming technology products themselves.
How AI Will Change Consumer Finance
Artificial intelligence may accelerate that transformation considerably.
Much of the first wave of digital banking focused on giving consumers remote access to financial information and transactions. The next phase is increasingly about using that information to provide recommendations, automate decisions and personalize financial experiences.
Banks and other financial companies are already using or exploring AI for applications such as:
- Personalized financial recommendations
- Customer-service assistants
- Fraud and scam detection
- Credit underwriting and risk assessment
- Spending analysis
- Automated savings and budgeting
- Product recommendations
- Document processing and loan servicing
Consumer expectations are beginning to move in the same direction. McKinsey’s 2025 Global Banking Annual Review found that more than half of consumers were already using generative AI tools, and many wanted their primary bank to offer AI capabilities as well. McKinsey also found that nearly all respondents said they would eventually consider switching providers if their bank failed to keep pace with the technological shift. (McKinsey & Company)
That does not mean consumers will automatically embrace every AI-powered financial product.
Financial decisions involve money, privacy, security and risk. A recommendation about a restaurant and a recommendation about taking out a mortgage carry very different consequences.
The financial institutions that use AI successfully will therefore have to understand not only what the technology can do, but where consumers are comfortable allowing it to make recommendations, automate actions or influence financial decisions.
That distinction makes consumer research increasingly important.
Why New Financial Products Need Concept Testing
Technology makes it easier to build new financial products. It does not make it easier to predict whether consumers will want them.
A feature can look compelling internally and still fail because customers find it confusing, unnecessary or untrustworthy. Conversely, consumers may strongly value a feature that initially appears minor to the product team. This is where consumer research can reduce the gap between what a financial services company assumes customers want and what the market actually demonstrates.
Consumer finance market research can combine qualitative methods such as focus groups and usability testing with quantitative research that measures preferences, behaviors and demand across larger consumer samples. Quantitative research can help financial institutions determine how widespread an attitude or behavior is, compare responses across customer segments and identify which new product concepts have the strongest potential before committing substantial resources to development and launch.
Usability Testing
Usability testing evaluates how people actually interact with a financial product or prototype.
Rather than asking whether someone says an app looks easy to use, researchers can observe whether users can successfully complete tasks such as opening an account, transferring money, locating a payment, understanding an AI recommendation or completing a loan application.
This can expose points of friction that product designers may not recognize internally.
For financial services, usability research is particularly important because confusion can become more than an inconvenience. Poor wording, unclear interfaces or misunderstood financial terms can affect consumers’ willingness to complete transactions or trust the institution.
Focus Groups
Focus groups allow researchers to examine the attitudes behind consumer behavior.
A bank considering a new AI financial assistant, for example, may want to understand:
- Which tasks consumers would trust it to perform
- Which financial decisions they still want to make themselves
- How consumers interpret the product’s value
- What language makes the product understandable
- Which privacy or security concerns could prevent adoption
Those are difficult questions to answer using behavioral data alone.
Focus groups are especially valuable during early product development, when companies are still refining the concept itself.
Quantitative Research
Focus groups can explain why consumers respond to a new financial product in a particular way, but financial institutions often also need to know how representative those reactions are. Quantitative research can provide that broader view through structured surveys and other forms of measurable consumer research.
For example, a financial services company testing several new product concepts could use quantitative research to measure purchase or adoption intent, rank preferred features, compare attitudes across demographic groups, evaluate pricing expectations or determine how many consumers share concerns identified during earlier focus groups.
Qualitative and quantitative research therefore often work best together. Focus groups, interviews and usability testing can uncover motivations and problems that researchers may not have anticipated, while quantitative research can test those findings across a larger sample and help financial institutions determine which insights are significant enough to influence product strategy.
In-Home Use Testing
In-home use tests can help researchers understand how financial products fit into consumers’ actual routines.
A financial product may behave differently in normal life than it does in a controlled testing environment. Consumers may use an app while paying bills at home, managing a household budget, shopping, discussing finances with a partner or responding to an unexpected expense.
Observing that context can identify behaviors and needs that consumers might not think to describe in a survey or focus group.
For digital financial products, the principle can extend beyond literal physical products: the objective is to understand how a service behaves when inserted into the consumer’s normal environment rather than evaluated only as an isolated concept.
Mall Intercepts and In-Person Interviews
Intercept research provides another way to gather rapid reactions from consumers in real-world settings.
Researchers can expose participants to a product concept, message, interface or prototype and immediately ask what they understand, expect or distrust.
This approach can be particularly useful when a financial services company needs feedback from consumers outside its existing customer base.
Digital research has expanded considerably, but in-person research still provides information that can be difficult to capture through a screen, including hesitation, confusion, body language and spontaneous follow-up discussion.
Consumer Finance Is Not Evolving the Same Way Everywhere
One of the largest mistakes a financial company can make is assuming consumers across different regions will respond to a new product in the same way.
Technology is global. Consumer behavior is not.
United States: Rapid Adoption and Intense Competition
The United States has a large and highly competitive digital financial-services market.
Consumers can choose among traditional banks, fintech companies, payment apps, digital lenders, investment platforms and increasingly technology companies that embed financial services into other products.
The Federal Reserve notes that instant payments, open banking and account-to-account payment products are among the developments currently reshaping U.S. consumer payments. (Federal Reserve)
That creates pressure on financial institutions to introduce new capabilities quickly, but speed can create its own risk. A product launched into a highly competitive market still has to demonstrate why consumers should use it instead of an existing option.
In the U.S., consumer finance research therefore often has to answer both a product question and a competitive one: does the customer understand the feature, and is it differentiated enough to change behavior?
Europe: Digital Growth Alongside Traditional Preferences
Europe demonstrates why “digital” and “traditional” should not always be treated as opposites.
- Digital payments continue to expand rapidly across the euro area. The European Central Bank reported that online payments represented 21% of consumers’ day-to-day payments in 2024, up from 17% in 2022, while electronic wallets and mobile applications represented 29% of online payment transactions. (European Central Bank)
- At the same time, traditional payment preferences remain significant. Cash was still used for 52% of point-of-sale transactions, and 62% of euro-area consumers said it was important to retain cash as a payment option. The ECB also found that 58% were concerned about privacy when making digital payments or conducting other banking activities. (European Central Bank)
For financial companies, the lesson is not that Europe rejects financial technology. It is that adoption can coexist with strong expectations regarding privacy, consumer choice and established financial behavior.
New products therefore need to be tested not simply for functionality, but for trust and fit within existing consumer habits.
Latin America: Rapid Digitization With Trust as a Critical Variable
Latin America is another region where broad assumptions can be misleading.
- Digital finance is expanding quickly. World Bank research found that fast-payment transactions across Latin America and the Caribbean increased from 620 million in 2017 to 79.8 billion in 2024, with fast payments accounting for 45% of regional digital-payment volume. (World Bank)
- The World Bank’s Global Findex 2025 also found that roughly 70% of adults in Latin America and the Caribbean have a financial account, with more than half using their account digitally through a card or mobile phone. (World Bank)
- The constraint is therefore not simply fear of new financial products. Trust, security and confidence matter considerably as adoption expands.
- A 2026 Mastercard study found that 89% of consumers in the region qualified as digital users, while 95% of digital users considered security important when choosing how to pay and 94% considered trustworthiness important. (Mastercard)
That makes market research especially useful for determining not simply whether consumers like a new financial product, but what protections, explanations and institutional signals they need before trusting it.
Asia-Pacific: Digital Leadership With Significant Local Variation
Asia-Pacific contains some of the world’s most advanced digital-finance ecosystems, but treating the entire region as one market would be equally misleading.
- The World Bank reported in 2025 that East Asia and the Pacific led developing regions in both digital connectivity and financial-service use, with 86% of adults owning a smartphone and 83% holding a financial account. (World Bank)
- The region is also at the forefront of payment infrastructure. The Bank for International Settlements found that Asia-Pacific is leading implementation of arrangements that link payment systems across borders. (Bank for International Settlements)
- Yet adoption remains uneven. The Asian Development Bank notes persistent differences in digital infrastructure, access and skills across Asia and the Pacific, including a 13-percentage-point gap in internet usage between urban and rural populations. (Asian Development Bank)
- Even digitally sophisticated consumers may still value human interaction for complex or high-stakes financial decisions. Accenture’s 2025 global banking study found that increasingly transactional digital banking relationships are creating demand for more personal experiences, with 73% of surveyed customers using institutions beyond their primary bank. (Accenture)
For research teams working across Asia-Pacific, this makes local qualitative research—including in-person interviews and focus groups—valuable when cultural context, financial literacy, trust or complex purchasing decisions cannot be understood from digital usage data alone.
Why Market Research Matters Before Creating Demand
Financial institutions often think of market research as a way to measure demand that already exists.
For emerging consumer financial products, it can play a larger role. Consumer research can combine qualitative methods such as focus groups with quantitative research to test new product concepts, measure demand and determine how broadly consumer preferences or concerns apply.
Research can help companies determine:
- Which consumer problem is actually worth solving
- Which features consumers value enough to change behavior
- How a new product should be explained
- Which concerns could prevent adoption
- How much human support consumers still want
- Which markets are most receptive
- How preferences differ by age, income or geography
- Whether a concept is ready for launch at all
That matters more as technology expands the number of products financial institutions could build. Quantitative research can help financial services companies distinguish between an interesting idea and a product with meaningful demand, while focus groups and other forms of consumer research can help explain why consumers respond to a concept the way they do.
AI can generate personalized financial insights. Open finance can allow customers to connect information across providers. Real-time payment systems can move money in seconds. Alternative data can change how companies assess credit. Digital interfaces can make products available almost anywhere.
None of those capabilities automatically creates demand.
Consumers still have to understand the product, believe it solves a problem, trust the institution providing it and feel comfortable changing their behavior.
That is where a consumer finance market research firm can become part of the product-development process rather than simply a measurement function at the end of it.
The Future of Consumer Finance Requires Consumer Understanding
Consumer finance is entering a period in which traditional financial products and emerging technology are increasingly difficult to separate.
Bank accounts will incorporate more automation. Credit products will become more personalized. Payments will become faster. AI will become more visible in financial decision-making. Digital experiences will continue replacing processes that once required branches, paperwork or direct employee interaction.
But financial technology remains ultimately dependent on human behavior.
A technically sophisticated product that consumers do not understand is not successful. Neither is a convenient product they do not trust or an innovative product that solves a problem consumers do not believe they have.
The financial institutions best positioned for the next generation of consumer finance will therefore combine technology development with continuous consumer research.
The question is no longer simply what can financial technology make possible?
It is which possibilities will consumers actually adopt—and why?
Frequently Asked Questions About Consumer Finance Market Research
What is consumer finance market research?
Consumer finance market research studies how individuals understand, choose and use financial products such as bank accounts, credit cards, mortgages, loans, payment services and digital financial tools. Research can include surveys, interviews, focus groups, usability testing and product-concept testing.
How will AI change consumer banking?
AI can make consumer banking more personalized and automated through financial recommendations, service assistants, fraud detection, underwriting, spending analysis and other tools. Adoption will depend heavily on whether consumers understand and trust these applications, particularly when AI influences important financial decisions.
Why should banks test new financial products before launch?
Product testing can identify usability problems, unclear messaging, trust concerns and features consumers do not value before a financial institution makes a larger investment in development or distribution. It can also identify differences between what product teams expect consumers to do and what consumers actually do.
Which research methods are useful for new financial products?
Useful methods can include usability testing, focus groups, in-depth interviews, surveys, intercept research and in-context product testing. The right combination depends on whether the company needs to evaluate behavior, attitudes, messaging, product usability or market demand.
Why do consumer financial products require regional research?
Payment behavior, technology adoption, regulation, trust, financial literacy and expectations differ significantly between countries and regions. A financial product that succeeds in one market therefore may require different positioning, functionality or customer support elsewhere.
Trust-Building Case Review
Pending SIS-provided client case study or first-party example. A relevant SIS project involving consumer financial-product research, concept testing, usability testing or regional financial-services research can be inserted here.